What to Do When Your Paycheck Disappears Before the Month Does
Rent goes up. Gas goes up. Groceries go up. Health insurance goes up. And your paycheck stays exactly the same.
If that’s where you are right now, you’re not bad with money. You’re doing math against numbers that don’t add up, and no amount of discipline fixes that.
Why I built this
I’m a teacher, and I’ve watched prices climb everywhere: gas, groceries, healthcare, utilities, childcare, etc. all while paychecks stayed flat. I’ve felt that squeeze myself, and I’ve watched it hit people close to me even harder.
I didn’t want to build another guide that tells you to skip your coffee or track every dollar in a spreadsheet you’ll abandon in a week. I wanted something that actually helps when the math doesn’t work, built from real conversations with people living exactly that, not guesswork.
Start here: what to pay first when money is short
This is one piece of what I built, and it’s yours right now, free, no strings attached.
When you can’t pay everything, paying things in the wrong order costs you more than being short in the first place. Late fees stack. Shutoffs cost more to reverse than they would have cost to prevent. Here’s the order that actually protects you:
- Housing. Rent or mortgage, first, always.
- Utilities that keep your home safe. Heat, electricity, water.
- Food and household basics.
- Transportation to work. Gas, car insurance, the car payment, whatever gets you to your job.
- Health. Prescriptions and insurance premiums.
- Childcare, if you need it to work.
- Minimum payments on debt. Credit cards, personal loans.
- Everything else.
Credit cards go near the bottom on purpose. A late fee on a card is a smaller problem than losing your housing, your power, or your way to work. If you’re already behind on something, it still goes in this order, a past-due electric bill is still a utility bill.
Write this list somewhere you’ll see it. It’s the first thing to reach for the next time a paycheck falls short.
But a list alone doesn’t get you through a bad month
That order tells you what to pay first. It doesn’t tell you what to do when even the first few things don’t fit. It doesn’t tell you what to say when you call a utility company to ask for more time, or how to find help with a medical bill, or what programs exist that you’ve never heard of because nobody hands you a list of them.
That’s the part a single blog post can’t cover. A real bad month needs an actual plan, not just one fact.
What I built for that
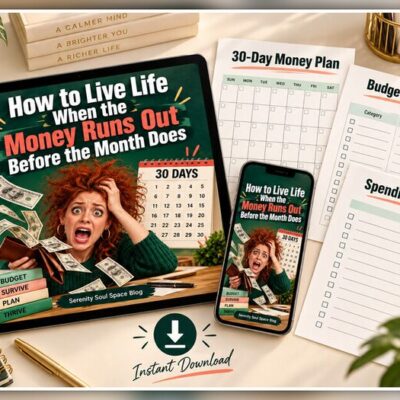
- A simple way to find out exactly what’s left after your essential bills, in about 20 minutes
- The full paid-first order above, plus a one-page Bad Month Plan you fill out once and use whenever things go sideways
- 19 word-for-word scripts, the exact words to say when you call a landlord, a utility company, a hospital billing office, or a debt collector
- A real map of assistance programs, food help, health coverage, energy bill help, rent help, medical bill assistance, with actual income limits, not vague pointers
- Small, honest ways to find breathing room, plus a check for a tax credit a lot of full-time workers qualify for and never claim
- 11 fillable worksheets you can type into right on your phone or print out
Every program and rule in it was checked against official government sources before it went in, because if I’m going to hand someone a guide that deals with their money and financial well-being, it has to be right.
Yours free: 11 fillable worksheets
If you’re not ready for the full guide yet, I also put together a free file with just the 11 worksheets, print-ready, no cost. It includes the “Bad Month Plan” and the bill tracker, so you have something to start with today.
If you’re ready for the rest
The full guide is $14.99. It won’t tell you that this is your fault, because it isn’t. It will give you a plan, the words for the hard calls, and a place to start.